What Accrual Accounting Means
In workforce operations, Accrual Accounting describes a record, report, statement, or audit within banking, payments, accounting, and funds movement. The definition becomes useful when it is connected to the actual facts and the action that follows.
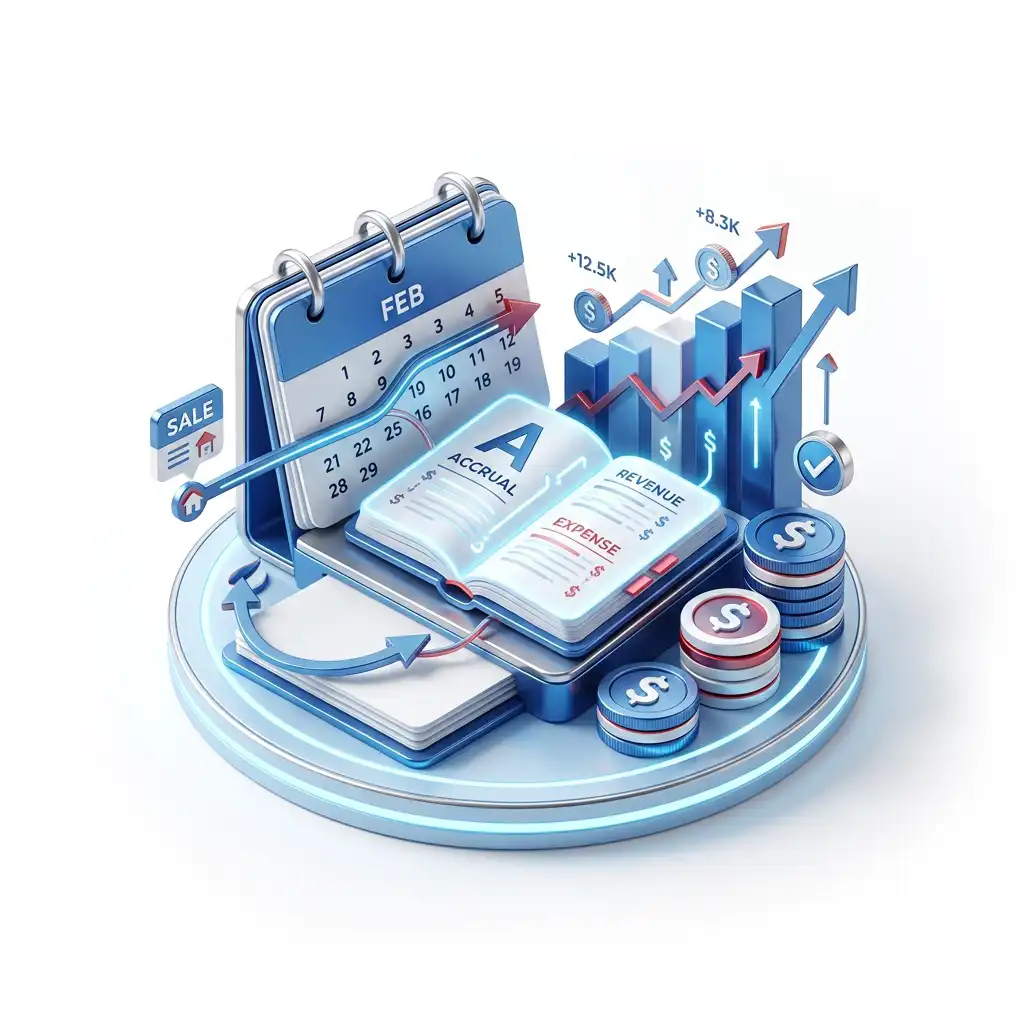
In plain language: Under the accrual method of accounting, income is generally recognized when earned and expenses when incurred, regardless of when cash is received or paid.
Important current information
Under the accrual method, income is generally recognized when earned and expenses when incurred, regardless of when cash is received or paid. The governing accounting or tax method and applicable rules still control the treatment of a specific item.
Why Accrual Accounting matters
A clear understanding of Accrual Accounting helps employees, managers, HR, payroll, finance, and administrators connect the same term to the correct facts and next action. Confusion can lead to incomplete records, delayed decisions, incorrect calculations, inconsistent treatment, or results that are difficult to explain.
The definition is a starting point, not a substitute for current law, agency instructions, a plan or contract, company policy, or the settings of a specific software product. The actual facts, effective period, jurisdiction, and controlling source determine how Accrual Accounting applies in a particular situation.
What to identify
- Subject: the person, organization, amount, event, status, document, or system record described by Accrual Accounting.
- Timing: the date, pay period, reporting period, effective period, or stage of the process.
- Source: the record, instruction, policy, plan, contract, order, or configuration that supplies the relevant facts.
- Responsibility: who enters, reviews, decides, approves, communicates, and corrects the information.
- Result: the schedule, time record, employee request, payment, filing, report, case, or system status affected.
How Accrual Accounting Works
Accrual Accounting becomes useful when the term is connected to the correct source, the people or records involved, and the action that follows.
Understand the term
Start with the definition above. Identify what Accrual Accounting describes, when it applies, what facts are required, and which result or decision depends on it.
Confirm the applicable source
Before relying on Accrual Accounting, confirm governing accounting method, income recognition event, the relevant period, and the source that controls the specific situation. A current agency instruction, plan, contract, policy, or system setting may add details that a glossary definition cannot cover.
Record the important facts
Identify the person or entity, period, amount or event, status, responsible role, and supporting information connected to Accrual Accounting. Keep the original facts and make missing or conflicting information visible for review.
Complete and preserve the result
Route the required decision to the appropriate owner, record any exception or correction, and connect the approved result to the affected schedule, timecard, payment, filing, report, case, or system record.
A useful check is to walk through one ordinary example and one exception. In both cases, another person should be able to understand the source facts, decision, correction history, and final result without relying on an undocumented explanation.
Practical Accrual Accounting Example
A simple scenario
Suppose an organization encounters Accrual Accounting during a routine banking, payments, accounting, and funds movement process. The responsible person confirms the defining point—“Under the accrual method of accounting, income is generally recognized when earned and expenses when incurred, regardless of when cash is received or paid.”—then checks the actual person or entity, relevant period, source record, applicable rule or configuration, and intended result. Any exception or correction is recorded before the information moves to the next step.
Consider a specialty manufacturer with 395 employees across 12 locations. The organization encounters Accrual Accounting during a normal workforce process. It first confirms what the term means in this situation, identifies the person or record involved, and checks the date or period to which the information belongs.
The matter is then assigned to process owner. That person reviews the source information, resolves missing or conflicting facts, records the reason for the decision, and confirms what happens next. Depending on the term, the result may affect a schedule, timecard, employee request, pay calculation, payment, filing, report, case record, or software setting.
The organization keeps Versioned source record and review date for Accrual Accounting and Accrual Accounting workflow event history with actor and timestamp so another authorized person can understand what happened. If the facts change or an error is found, the correction is linked to the original record and carried through to any affected result. This example is illustrative; current law, agency instructions, contracts, plans, policies, and software settings still control the real situation.
What Employers Should Know About Accrual Accounting
The amount of process needed for Accrual Accounting depends on its risk and use. A simple informational label may need little more than a clear definition, while a term that affects pay, benefits, taxes, legal rights, safety, or financial reporting usually needs stronger review and documentation.
- Confirm the scope: Identify exactly what Accrual Accounting describes, the people or records involved, the effective period, and any circumstance that changes the meaning.
- Use a current source: Check the applicable agency instruction, law, plan, contract, company policy, form, or software setting before making a decision that depends on Accrual Accounting.
- Assign responsibility: Name who supplies the facts, who reviews them, who approves the result, and who corrects or reconciles the downstream record. A typical owner is subject-matter owner.
- Keep useful records: Retain enough information to explain the outcome, including Versioned source record and review date for Accrual Accounting; Accrual Accounting workflow event history with actor and timestamp; Accrual Accounting exception log, aging, disposition, and reviewer.
- Handle exceptions visibly: Give missing, late, duplicate, disputed, corrected, or out-of-period information a clear status, responsible person, reason, and next step instead of resolving it through an undocumented workaround.
Access should also match the sensitivity of the information. Limit changes to authorized people, preserve meaningful before-and-after history, protect personal information, and make corrections traceable to the record they changed. When Accrual Accounting affects another system or team, confirm that the approved result reaches the correct destination.
How Accrual Accounting Connects to TimeTrex
TimeTrex can help connect information about Accrual Accounting with the workforce records and people who use it. Depending on the term, relevant capabilities may include TimeTrex payroll software, TimeTrex workforce management features, and TimeTrex workforce management software.
A useful setup starts with the source of the information, the person allowed to review or approve it, and the record that should receive the result. Permissions should limit sensitive changes, while timestamps, status history, notes, reports, and integrations should make important updates understandable. Any exception should remain visible until the responsible person resolves it.
The exact TimeTrex configuration depends on the organization, edition, integrations, policies, and applicable requirements. Confirm that the selected features support the intended Accrual Accounting process, test an ordinary case and an exception, and make sure the final schedule, time, payroll, employee, or reporting record matches the approved information.
Frequently Asked Questions
What does Accrual Accounting mean?
Under the accrual method of accounting, income is generally recognized when earned and expenses when incurred, regardless of when cash is received or paid. In workforce operations, the term is used within banking, payments, accounting, and funds movement.
Why does Accrual Accounting matter?
Accrual Accounting matters because people need a shared way to identify the correct facts, responsible person, time period, and next action. A clear meaning reduces incomplete records, delays, inconsistent decisions, and downstream corrections.
What is a practical example of Accrual Accounting?
Suppose an organization encounters Accrual Accounting during a routine banking, payments, accounting, and funds movement process. The responsible person confirms the defining point—“Under the accrual method of accounting, income is generally recognized when earned and expenses when incurred, regardless of when cash is received or paid.”—then checks the actual person or entity, relevant period, source record, applicable rule or configuration, and intended result. Any exception or correction is recorded before the information moves to the next step. The organization then keeps enough information to explain the decision and correct any affected record.
Who is responsible for Accrual Accounting?
Responsibility depends on the organization and the situation. A typical owner is subject-matter owner, with additional review from HR, payroll, finance, legal, benefits, safety, or a system administrator when the term affects those areas.
What records support Accrual Accounting?
Useful records usually include the original source, applicable period, person or entity involved, required facts, reason for the decision, approval or communication, correction history, and final result. Examples may include Versioned source record and review date for Accrual Accounting and Accrual Accounting workflow event history with actor and timestamp.
How can TimeTrex support work involving Accrual Accounting?
TimeTrex can help connect workforce information, permissions, employee and manager actions, time or schedule records, payroll results, and reports where those capabilities are relevant. The organization should confirm feature availability, configuration, integrations, and current requirements for its specific use.
Sources and Verification
Use the sources below to understand Accrual Accounting and confirm details that can change. Current forms, rates, thresholds, dates, eligibility rules, jurisdictional obligations, plan provisions, payment rules, and software behavior should be checked before action.
TimeTrex glossary
Browse clear definitions for HR, payroll, scheduling, timekeeping, benefits, and workforce-management terms. Open the TimeTrex glossary
Publication 538, Accounting Periods and Methods
Use Publication 538 for federal tax accounting methods and timing rules. Open the Internal Revenue Service resource
Publication 583, Starting a Business and Keeping Records
Use Publication 583 for federal recordkeeping and accounting-method context. Open the Internal Revenue Service resource
Use the bank or payment-network operating rules for transaction handling and the tax or labor authority for the underlying liability.